Muni parcel-tax debate turns from the ballot to service and accountability
Proposition H proposes 15 years of operating revenue. Property rules, renter pass-throughs, administrative costs and service plans determine its practical effects.
San Francisco's Proposition H ties a new local tax to one of the city's most immediate service questions: how to keep Muni operating as temporary funding runs out. The November 3 measure proposes a parcel tax lasting from July 2027 through June 2042. It is a financing proposal for ongoing service, not simply a bond for building a new piece of infrastructure.
The controller's fiscal analysis estimates roughly $177 million in annual revenue at the start, based on the parcel data available when the statement was prepared. That is a projection, not a recorded receipt. Exemptions, property records, inflation adjustments and administration would affect the amounts actually collected.
This article examines the measure's tax design and service-accountability questions after the election, without making an independent result call. Our San Francisco politics coverage separates three issues often bundled together: the need for transit, the design of this particular tax and the performance of the agency receiving it.
Operating money pays for a continuing service
A transit system needs money to operate vehicles, maintain equipment and support the work that makes scheduled service possible. A one-time capital project and a recurring operating budget answer different needs. New infrastructure does not by itself pay the employees who run a route after it opens.
The official title and summary says the tax revenue would be restricted to administration and transit operations. The legal text provides the detailed spending and oversight rules. Residents should examine those provisions rather than assume that every activity under a transportation agency's name is funded in the same way.
A recurring tax can improve budget predictability, but predictability is not the same as adequacy. Costs can rise faster than receipts, and other funding sources can change. A 15-year authorization therefore does not establish that the agency's finances are settled for 15 years.
The public should be able to see the proposed revenue alongside the rest of the operating plan. If a new receipt replaces another source rather than adding to it, the net change can be smaller than the tax total. That possibility needs to be checked in adopted budgets, not assumed in either direction.
The tax is based on property size and type
The measure uses building area and parcel classifications rather than a simple percentage of a property's assessed value. The official summary sets different starting amounts and marginal rates for different kinds of property. It also includes caps and exemptions that affect what individual owners would pay.
For a single-family residential parcel with up to 3,000 square feet of building area, the starting annual amount would be $129. Larger homes would face additional marginal charges. Multifamily and commercial parcels follow different schedules. Quoting only the single-family starting amount as the bill for every property would be inaccurate.
The design raises a legitimate fairness question. Building area can be easier to observe than a household's ability to pay, but two owners of similarly sized buildings can have very different incomes and wealth. A property tax exemption or reduction may change that comparison, depending on who qualifies and who applies.
A useful public explanation would provide examples labeled by property type and size, with the applicable exemptions clearly stated. It should not choose only the smallest bill or the largest theoretical bill. Residents need to understand the calculation that applies to their own circumstances.
Renters can be affected as well as owners
The measure includes rules governing what landlords of rent-controlled units may pass through to tenants. The official documents describe a limit of half the tax, capped at $65 per unit annually for covered tenancies, with qualifications and exceptions. The details should remain beside the headline amount.
A tax assessed on a property owner can therefore have a direct, legally permitted effect on some renters. That is different from a general economic claim that every cost will eventually be passed through. The first is a rule in the measure; the second would require evidence about market behavior and cannot simply be assumed.
Administration matters here. Tenants and owners would need clear notices, a way to identify whether a unit is covered and a process for correcting an improper charge. A small annual amount can still create a dispute if the parties cannot determine what the law allows.
Senior-owner provisions and other exemptions also require clear implementation. The controller notes that the revenue estimate depends in part on exemptions requested and granted. A forecast should not be read as a promise that every eligible person will apply correctly or that the property database contains no errors.
Supporters prioritize service continuity
GrowSF supports Proposition H, arguing that dedicated revenue is preferable to a recurring fight over how to cover Muni's operating gap. It also identifies reservations about aspects of the tax design, illustrating that support does not require agreement with every exemption or burden.
The strongest service case is that transit availability affects more than the people inside a vehicle on a particular trip. A reliable network can shape access to jobs, schools, care and shopping. A route can matter to someone who uses it occasionally but needs it when other options fail.
That argument should still be tied to a defined service plan. A tax dedicated to operations does not tell a resident how often their bus will arrive or which evening trips will run. Officials should show the service level supported by the adopted budget and explain changes from the previous schedule.
The San Francisco Public Press analysis of Proposition H and the regional measure describes the interconnected funding strategy. The local parcel tax and a regional sales tax are separate measures with separate rules. Their revenues should not be combined without explaining which jurisdiction collects them and which agencies receive them.
Opponents want more discipline before a new commitment
ConnectedSF opposes Proposition H, arguing that the agency should pursue additional efficiencies and match spending to service needs before residents take on a long-term tax. That is a policy position, not proof that every proposed saving is available without affecting riders.
A useful evaluation would examine specific savings proposals. Cutting an unfilled position may have a different effect from reducing a staffed route. A job title described as administrative may perform work needed for safety, maintenance or scheduling. Conversely, calling every expense essential would prevent meaningful review. The task is to identify the function and the consequence of changing it.
Opponents also question whether oversight provisions require corrective action or merely produce reports. That distinction can be checked in the legal text. An independent review is valuable, but its existence does not show that recommendations will be adopted. Residents should be able to track management's response and any decision not to act.
Our editorial standards require the same scrutiny of a warning about service cuts and a promise of painless savings. Both are claims about an alternative future. Neither should be presented as a measured outcome before the underlying choices have been made.
Tax administration is part of the cost
The controller estimates one-time startup costs and continuing administrative expenses. Those include maintaining property data, handling exemptions and managing appeals. They are a reason to distinguish gross tax receipts from money available for service after collection costs.
An area-based tax also makes data quality consequential. A dispute about building size or use can become a dispute about the bill. Public guidance should explain the source of the records, how owners can inspect them and how errors are corrected. An accurate tax schedule cannot compensate for an inaccurate input.
Oversight should follow both revenue and outcomes. A spending report can establish that money went to permitted activities. A service report can show whether scheduled trips occurred and whether riders received the promised frequency. Neither document replaces the other. A fully compliant expenditure can still deliver weak service, while a service improvement does not excuse improper use of restricted money.
Service comparisons should also show variation among routes and times of day. A systemwide average can improve while a rider’s late-evening connection becomes less usable. Likewise, an increase in total trips may reflect growth on busy lines without restoring service elsewhere. A public dashboard should allow residents to distinguish frequency, reliability, crowding and access, because those measures answer different questions. Reporting the change from a clearly dated baseline would let both supporters and critics test their claims without selecting only the most favorable part of the system.
The next test is a budget tied to results
No representative survey of voters' reasons for their choices on Proposition H was reviewed for this article. The competing positions described here are published organizational arguments, not a citywide poll. The 567politics methodology explains why projections, selected reactions and observed results must be kept separate.
The public record after the election should connect the legal result to the operating budget, the tax administration plan and the service schedule. Where officials rely on another measure or a loan, they should state that dependency. Where a projected shortfall changes, the new estimate should identify the period and assumptions.
Across the local politics section, the same test applies to recurring service taxes: what is collected, what is spent and what residents receive. For Muni, a durable funding source would be the start of that accountability chain, not the end of the inquiry into reliable public transportation.
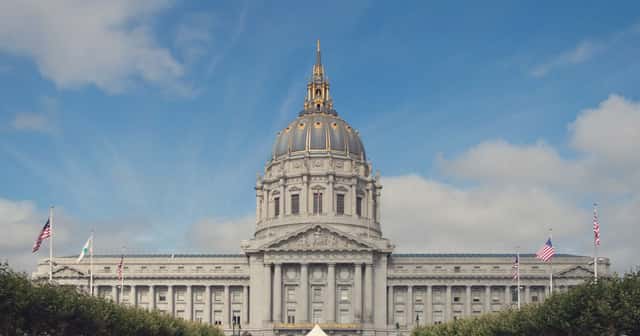
Photo: San Francisco City Hall, July 2015, by Supercarwaar, CC BY-SA 4.0, via Wikimedia Commons. Displayed with a crop; archival image.

Differing perspectives
Should San Francisco fund Muni operations through the proposed 15-year parcel tax?
Each position is summarized as its supporters make it, with equal weight and in alphabetical order. A summary is not an endorsement; the evidence for each is weighed in the story above.
Require more reform before new taxes
Who holds it: ConnectedSF
Residents should not take on a long-term tax before the agency demonstrates stronger spending discipline and a clear service plan. Opponents call for specific efficiency measures, scrutiny of costs and accountability that leads to action rather than relying mainly on additional revenue.
In their words: ConnectedSF voter guide ↗
Secure dedicated operating revenue
Who holds it: GrowSF and Proposition H supporters
A dedicated source of operating money would help sustain transit service and reduce repeated competition with other city services for funding. Supporters argue that reliable transit has benefits across the city, while the measure includes a time limit and oversight requirements.
In their words: GrowSF voter guide ↗
READ BEYOND 567POLITICS
Alternate sources & perspectives
Independent coverage and primary evidence to help you compare arguments. A link is not an endorsement; perspective labels describe the linked material.
- primary evidence
Controller's fiscal analysis ↗
City and County of San Francisco
Official legal or fiscal document reviewed; forecasts are not observed outcomes.
- primary evidence
Official title and summary ↗
City and County of San Francisco
Official legal or fiscal document reviewed; forecasts are not observed outcomes.
- primary evidence
Legal text ↗
City and County of San Francisco
Official legal or fiscal document reviewed; forecasts are not observed outcomes.
- other perspective
GrowSF supports Proposition H ↗
GrowSF
Organization’s own policy argument; does not represent a survey of residents.
- independent analysis
San Francisco Public Press analysis of Proposition H and the regional measure ↗
San Francisco Public Press
Independent local reporting; preliminary results must not be treated as certified.
- other perspective
ConnectedSF opposes Proposition H ↗
ConnectedSF
Organization’s own policy argument; does not represent a survey of residents.
Reviewed 2026-11-04. Reviewed November 4, 2026. Official legal/fiscal PDFs were retrieved from media.api.sf.gov, with source text archived alongside the draft. SF.gov HTML was bot-gated. No independent election call, voter-opinion survey, interviews or government-data API pull is claimed. Attributed campaign arguments are not facts about all residents. Public record and source-specific limitations appear in the body.